


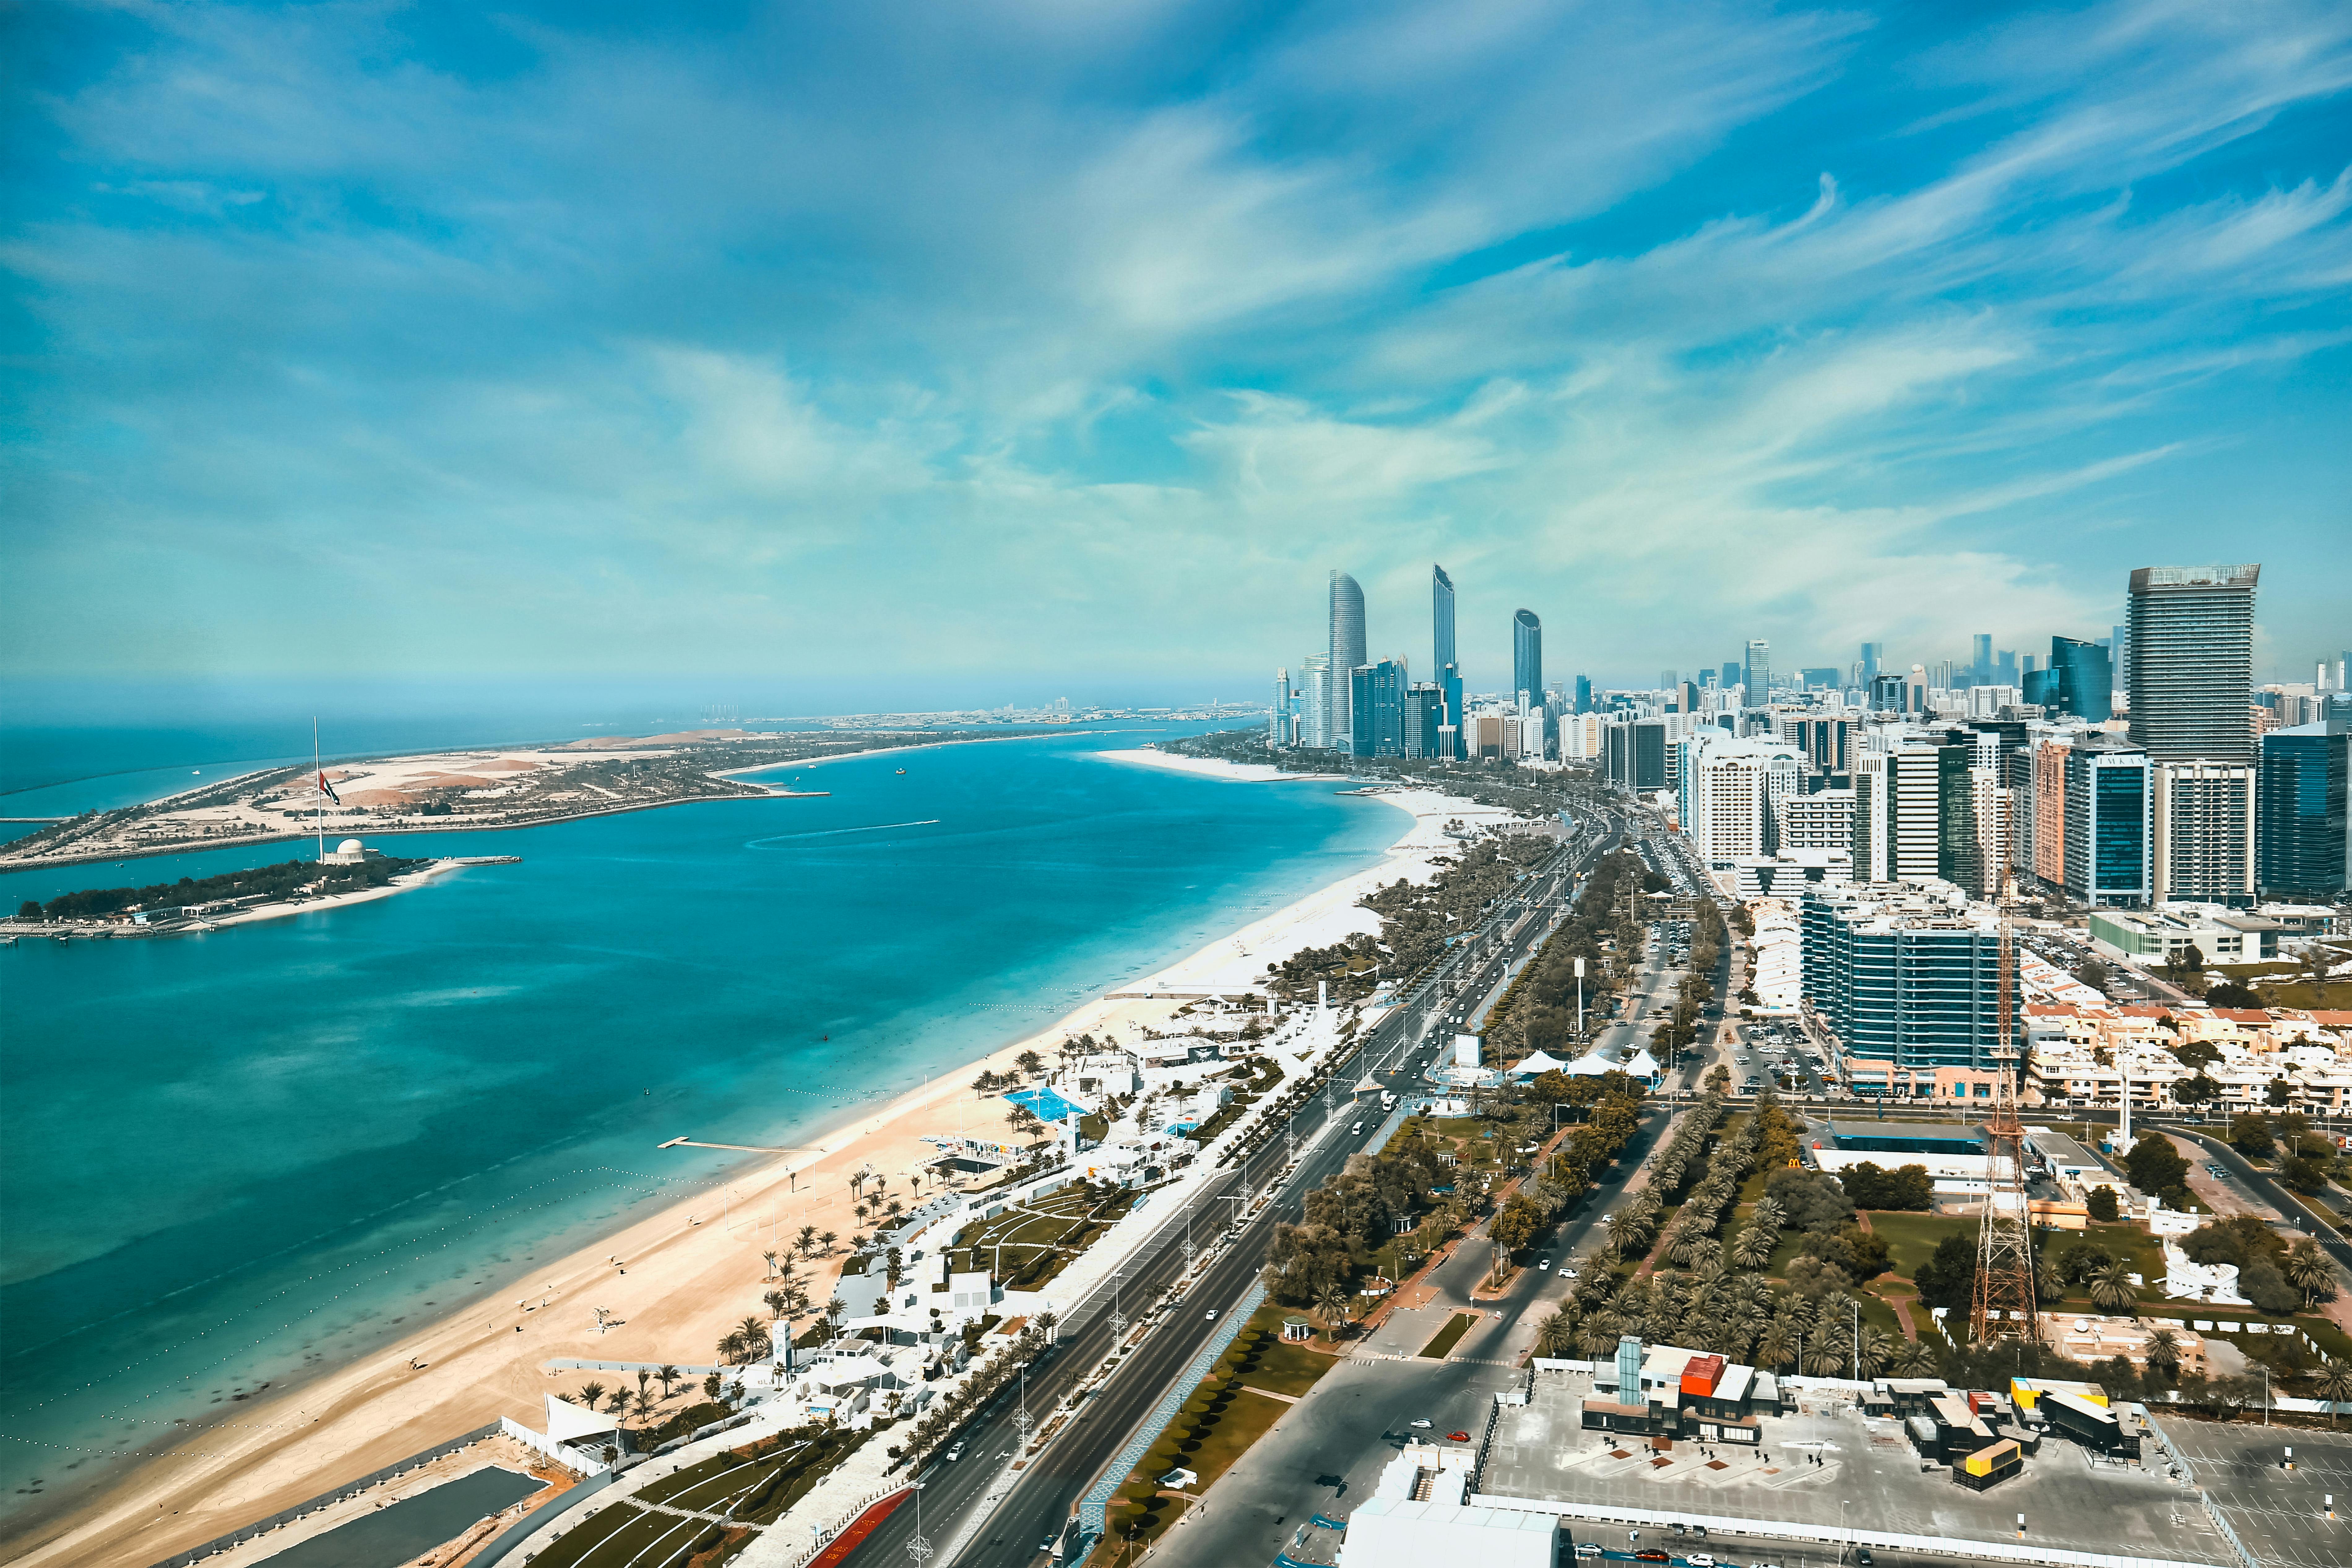
bu Dhabi’s residential real estate market has entered a sharp growth phase, with average prices up 17.3% year on year as of Q2 2025. This performance reflects a rare convergence of global capital inflows, constrained near term supply and a deepening shift in investor behaviour towards the UAE’s political stability, tax efficiency and lifestyle appeal.
From Saadiyat Island villas to Reem Island apartments, momentum is broadening across both the primary and secondary markets, creating opportunities for well capitalised investors to position ahead of sustained upward pricing pressure.
Market performance
| Segment | AED / кв. фут | Quarter on quarter |
|---|---|---|
| Overall residential | 1,230 | +6.4% |
| Апартаменты | 1,296 | +6.8% |
| Виллы | 1,103 | +3.4% |
Overall residential prices rose 17.3% year on year and 6.4% quarter on quarter. Cumulative appreciation of 31.3% since Q1 2020 outpaces many global gateway cities.
Apartments rose 6.8% in the quarter to AED 1,296 per sq ft, matching the market’s overall 17.3% annual gain, with the strongest growth in high-demand, master-planned communities.
Villas rose 3.4% in the quarter to AED 1,103 per sq ft overall, with standout growth in premium submarkets: Saadiyat Island up 28% and Yas Island up 22% year on year. Demand is driven by the scarcity of prime waterfront plots and lifestyle-led migration.
Secondary market strength
Established communities such as Yas Island, Raha Beach, Ghadeer, Al Reef and Reem Island recorded price increases of 20 to 30% year on year. Several trophy developments posted gains above 30%, fuelled by cash-ready buyers competing for limited resale stock.
Demand drivers
Global capital migration. Абу-Даби стал вторым после Дубая направлением в ОАЭ для иностранных инвестиций в недвижимость: за последние 12 месяцев он привлек 1,6 млрд долларов США частного капитала.
High-net-worth engagement. The proportion of HNWIs planning to buy in Abu Dhabi rose from 14% to 19% in the last year. Among UHNW brackets, 75% of the USD 30 to 50M wealth segment are looking to purchase, and 65% of those above USD 50M are actively seeking acquisitions.
Supply constraints. Only 890 new units were delivered in H1 2025, against a construction pipeline of 33,000 units through 2029. Short term supply tightness is expected to sustain upward pricing pressure.
Quality of life and stability. Master-planned communities, waterfront living and cultural infrastructure remain central, while Abu Dhabi’s political stability and zero personal income tax remain strong attractors.
The combination of accelerating capital inflows, scarcity of immediate supply and broadening investor participation is creating a compounding effect on both price appreciation and rental yields.
Key strategic plays for investors
- Early entry. Under-construction prime projects in Saadiyat and Yas, to capture development-stage pricing ahead of completion.
- Targeted secondary acquisitions. Assets where price momentum is already 20%+ year on year, particularly in waterfront or lifestyle-led communities.
- Portfolio balance. Villas in premium zones for capital preservation and long term appreciation, paired with apartments in high-yield districts for cash flow.

