


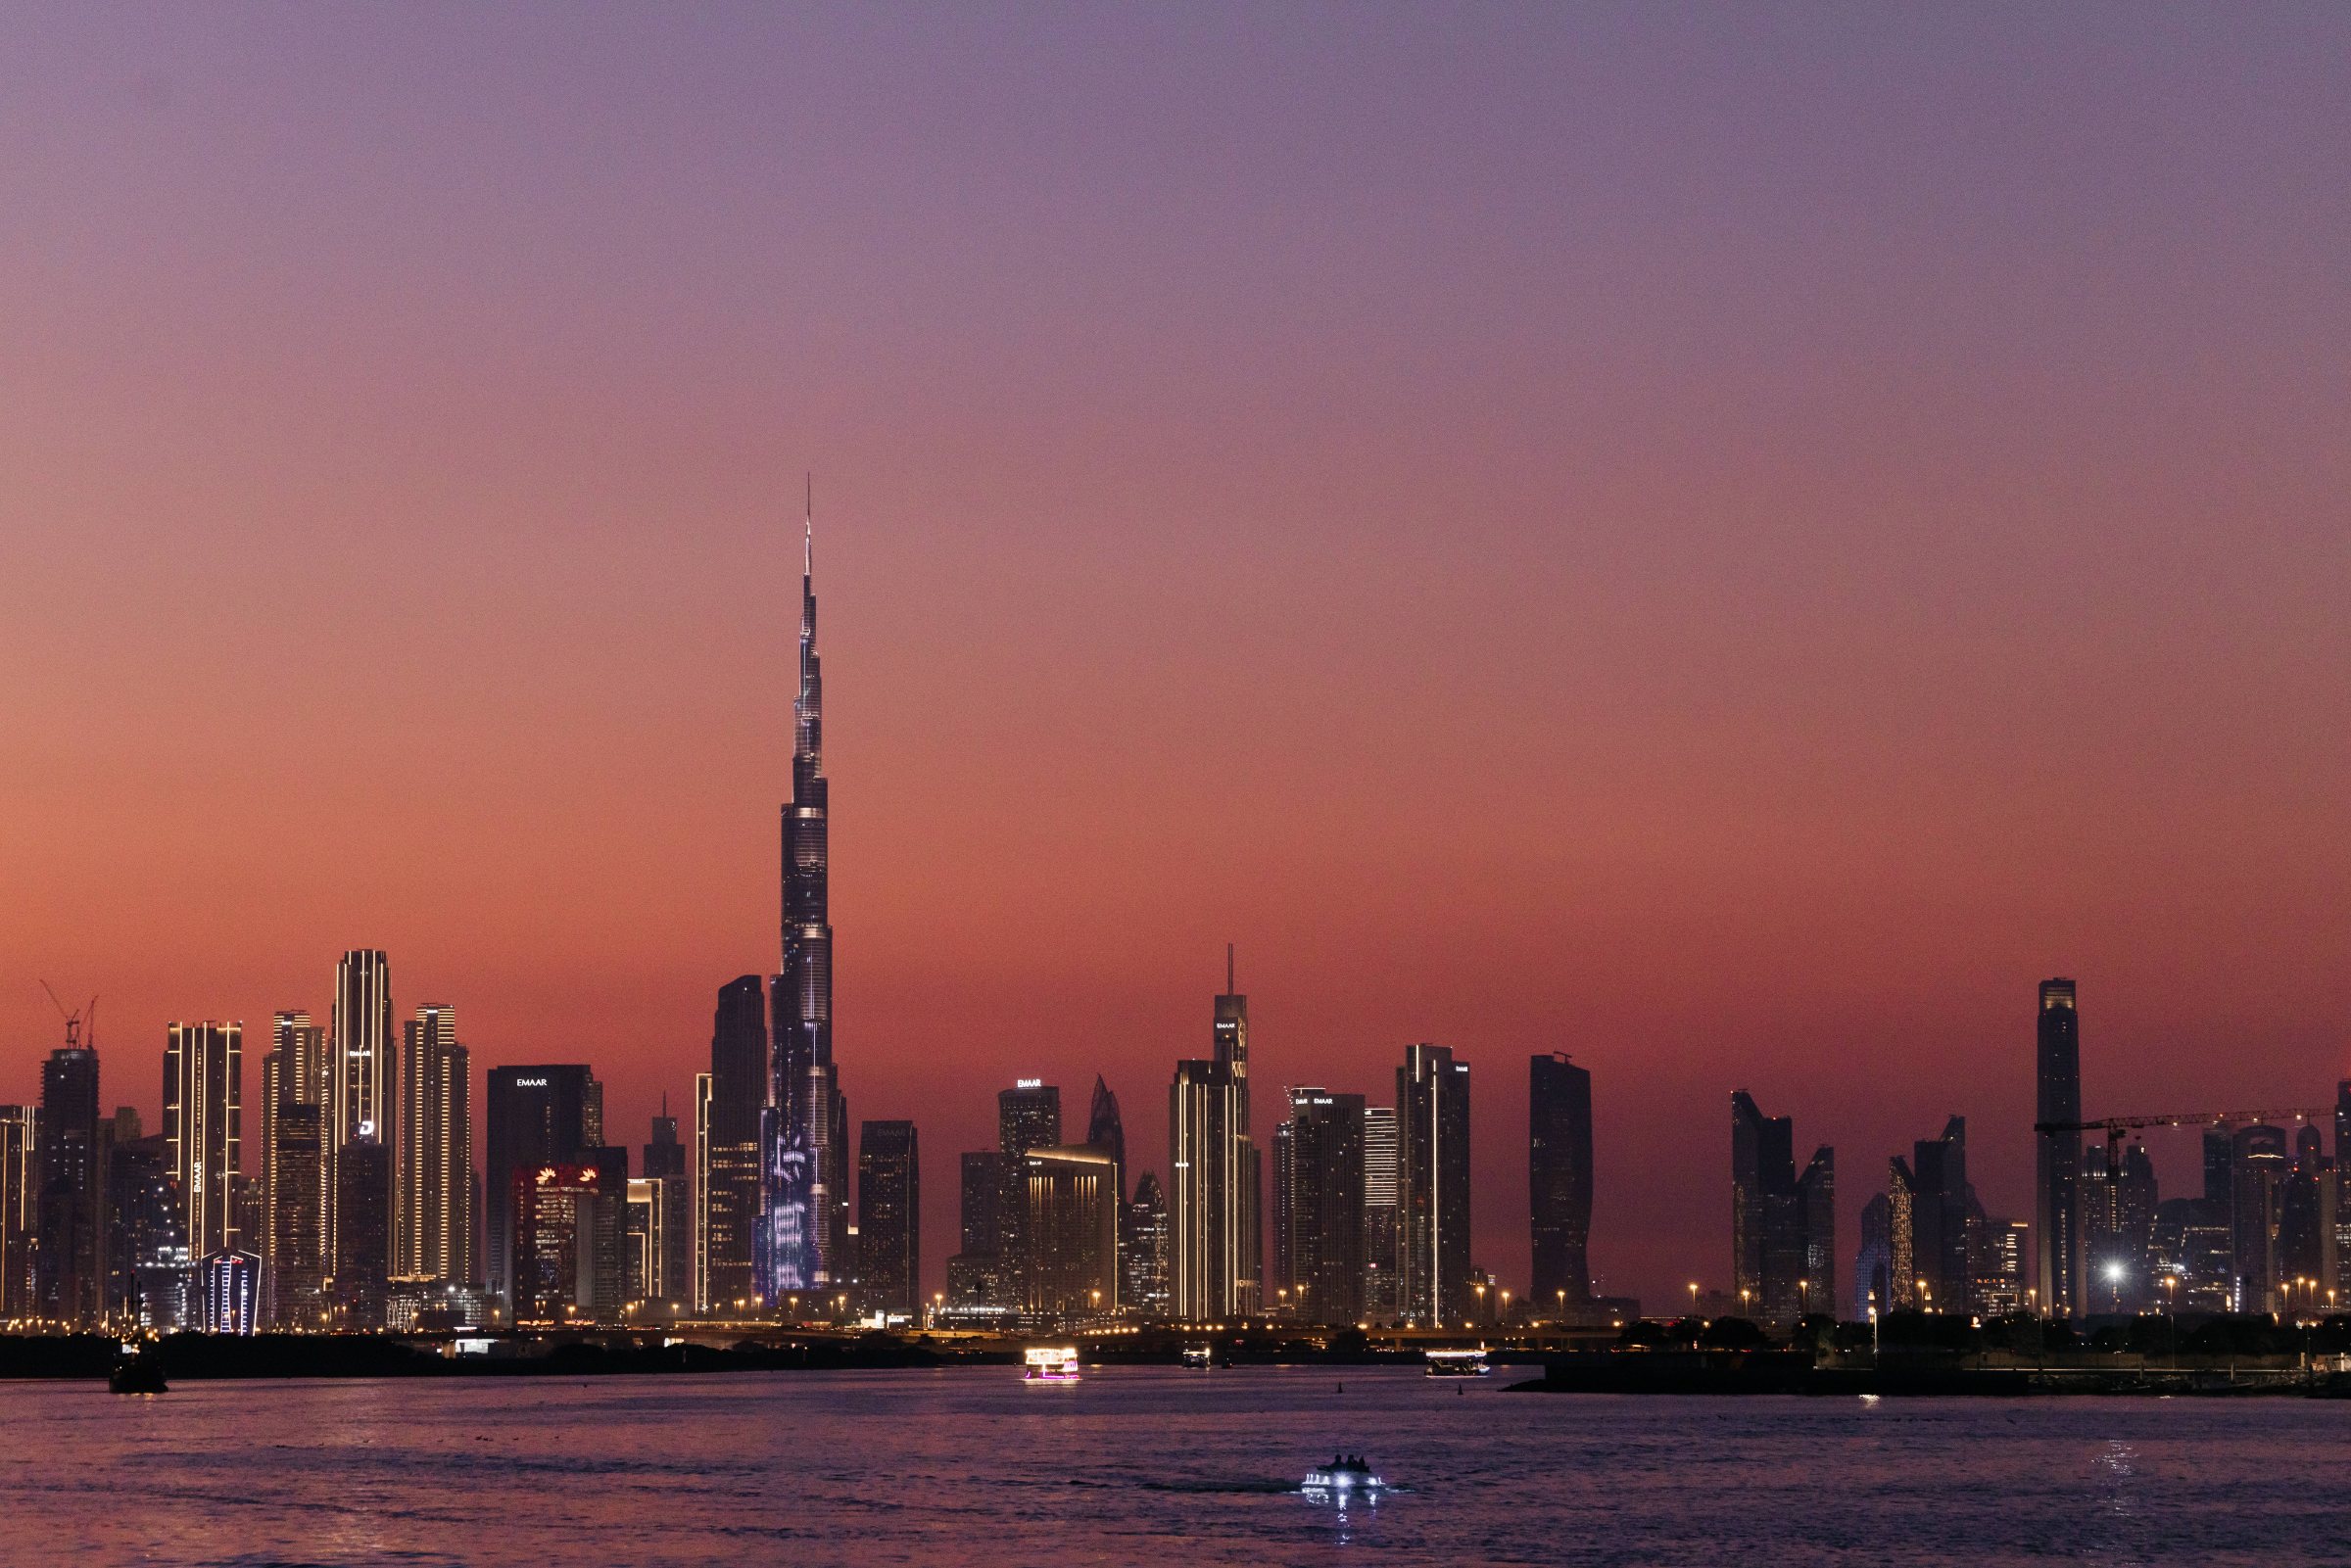
n the first half of 2025, Dubai real estate transactions exceeded USD 117 billion, a 25% year on year increase that confirmed to global investors that Dubai remains one of the world’s most compelling real estate markets.
Beneath the record figures, a subtler story is unfolding, defined by strategic discernment rather than exuberance.
Поверхность: Сила в количестве
At face value, the Dubai property market appears exceptionally strong. Transaction volume is up, demand for luxury, branded and waterfront residences remains buoyant, off-plan launches continue to attract international capital and rental yields have strengthened further in prime freehold areas.
A confluence of macro forces drives this growth: regional stability, long term residency schemes and Dubai’s positioning as a haven for wealth and talent. For high net worth investors seeking both performance and geopolitical safety, the city is increasingly a primary choice rather than a peripheral one.
Подводное течение: рынок взрослеет
Alongside this growth, a measured recalibration is under way. Data from Q3 2025 shows the first signs of stabilisation in some sub-markets, and negotiation windows are opening selectively, particularly in the secondary market, where pricing is beginning to meet buyer resistance.
The off-plan segment still commands a premium, but resale opportunities are gaining traction. This signals a maturing market in which short term momentum is giving way to long term value strategies.
Стратегия для состоятельных инвесторов: не просто момент, а верный момент
The Dubai real estate story in 2025 is about timing well rather than timing the peak.
For seasoned investors, the question is where to allocate with precision rather than whether to enter. The city’s most resilient value lies in supply constrained, lifestyle anchored enclaves: Dubai Maritime City, Jumeirah Bay, Palm Jumeirah, Dubai Marina, Downtown, select pockets of Business Bay and District One. These are mature, largely built out markets where natural scarcity preserves long term value. Corrections, when they occur, are typically brief and absorbed by sustained demand.
| Segment | Representative areas | Direction |
|---|---|---|
| Supply constrained, lifestyle anchored | Dubai Maritime City, Jumeirah Bay, Palm Jumeirah, Dubai Marina, Downtown, District One | Resilient |
| High density, emerging freeholds | JVC, JVT, Dubai Sports City, Arjan, Al Furjan, parts of Dubailand | Slowing momentum |
In emerging zones and high density freeholds, buyer behaviour is shifting. Capital is becoming more selective, moving away from speculative volume towards proven quality. Areas such as Jumeirah Village Circle, Jumeirah Village Triangle, Dubai Sports City, Arjan, Al Furjan and parts of Dubailand are experiencing slower momentum. These locations, often characterised by oversupply and uneven delivery, are no longer supported by market wide optimism. Investors should prioritise developer reputation, delivery track record and the lived experience of the end user, as well as finishes.
Вне плана и вторичное жилье: переосмысление разделения
For years, off-plan investment in Dubai was driven by first mover advantage. Today, the calculus is more exacting.
Discerning off-plan buyers are focusing on genuine differentiators: branded partnerships, architectural distinction and rare positioning. At the same time, the secondary market is reintroducing value for the first time in over a year, particularly where holding periods are longer and seller motivation is rising.
The opportunity is to build a portfolio that balances both: off-plan for future rarity and secondary for present value, weighted by liquidity strategy and long term legacy rather than enthusiasm.
The Redwood View: инвестиции в то, что остается
At Redwood Heritage, we interpret market developments with clarity and act with conviction.
Dubai real estate in 2025 is dynamic and maturing. This is a more intelligent phase, in which depth, durability and discretion matter more than ever.
Это значит:
- Приоритет активам поколений: тем, что сохраняют ценность на протяжении поколений, а не только рыночных циклов
- Чтение регуляторных сигналов, в том числе решения муниципалитета Дубая сдержать неоправданную гонку в архитектурных решениях
- Гибкость в распределении капитала: баланс ликвидности, доходности и долгосрочной полезности
Our counsel remains unchanged: invest in what will last rather than in what is loudest.
For deeper insight or personalised portfolio guidance, Redwood clients may request a private market briefing at their convenience.

